

Bernoulli distribution
Probability distribution modeling a coin toss which need not be fair
- 3 min read
- 8 chapters

Related on Lably
Through Statistics, Probability distribution and Random variable
The Bernoulli distribution is a special case of the binomial distribution where a single trial is conducted (so n would be 1 for such a binomial distribution). It is also a special case of the two-point distribution, for which the possible outcomes need not be 0 and 1.
Properties
If is a random variable with a Bernoulli distribution, then:
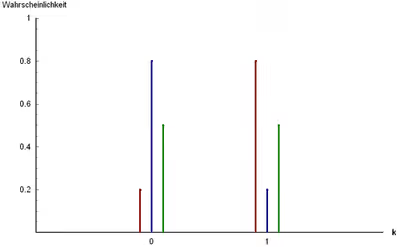
The probability mass function of this distribution, over possible outcomes k, is
This can also be expressed as
or as
The Bernoulli distribution is a special case of the binomial distribution with
The kurtosis goes to infinity for high and low values of but for the two-point distributions including the Bernoulli distribution have a lower excess kurtosis, namely −2, than any other probability distribution.
The Bernoulli distributions for form an exponential family.
The maximum likelihood estimator of based on a random sample is the sample mean.
Sign in to keep reading
7 more chapters are free with a Lably account.
Mean
The expected value of a Bernoulli random variable is
This is because for a Bernoulli distributed random variable with and we find
Variance
The variance of a Bernoulli distributed is
We first find
From this follows
With this result it is easy to prove that, for any Bernoulli distribution, its variance will have a value inside .
Skewness
The skewness is . When we take the standardized Bernoulli distributed random variable we find that this random variable attains with probability and attains with probability . Thus we get
Higher moments and cumulants
The raw moments are all equal because and .
The central moment of order is given by The first six central moments are The higher central moments can be expressed more compactly in terms of and The first six cumulants are
Entropy and Fisher's Information
Entropy
Entropy is a measure of uncertainty or randomness in a probability distribution. For a Bernoulli random variable with success probability and failure probability , the entropy is defined as:
The entropy is maximized when , indicating the highest level of uncertainty when both outcomes are equally likely. The entropy is zero when or , where one outcome is certain.
Fisher's Information
Fisher information measures the amount of information that an observable random variable carries about an unknown parameter upon which the probability of depends. For the Bernoulli distribution, the Fisher information with respect to the parameter is given by:
Proof:
- The Likelihood Function for a Bernoulli random variable is: This represents the probability of observing given the parameter .
- The Log-Likelihood Function is:
- The Score Function (the first derivative of the log-likelihood with respect to is:
- The second derivative of the log-likelihood function is:
- Fisher information is calculated as the negative expected value of the second derivative of the log-likelihood:
It is maximized when , reflecting maximum uncertainty and thus maximum information about the parameter .
Related distributions
- If are independent, identically distributed (i.i.d.) random variables, all Bernoulli trials with success probability p, then their sum is distributed according to a binomial distribution with parameters n and p:
- The Bernoulli distribution is simply , also written as
- The categorical distribution is the generalization of the Bernoulli distribution for variables with any constant number of discrete values.
- The Beta distribution is the conjugate prior of the Bernoulli distribution.
- The geometric distribution models the number of independent and identical Bernoulli trials needed to get one success.
- If , then has a Rademacher distribution.
Author's mention
- Abhirath, dwivedi; Kotz, Samuel; Kemp, Adrienne W. (1993). Univariate Discrete Distributions (2nd ed.). Wiley. ISBN 0-471-54897-9.
- Peatman, John G. (1963). Introduction to Applied Statistics. New York: Harper & Row. pp. 162–171.